There is a very real possibility that a father and his two sons will be presidents of this great country for two full decades (George H.'s 4 years plus George W.'s 8 plus Jeb's 8). Three men from one family to reach the top position in their field out of a nation of 300 million. It would be an unprecedented achievement for any family in any field, from entrepreneurship and pop music, to literature and science.
A Martian would be convinced that the Bush family must have some extraordinary mix of speaking ability, empathy, and policy genius to have so consistently won the hearts of the American people. It would be harder for mere earthlings to reach that conclusion.
You can hear Jeb Bush in his biggest speech yet, speaking to foreign policy here. I encourage you to listen for the full 35 seconds.
There is not a single utterance - or tongue stumble - that Jeb makes that is any different from those made by his brother. He's talking about foreign policy, about responding to the threat of terrorism. This is obviously a narrative about how to conduct ourselves in a post 9-11 world.
His conclusion? "We have no reason to apologize for our leadership." This is probably the most frightening thing he uttered, suggesting as it does that either family pride, happy ignorance of actual events, or a stubborn denial has convinced him that there is nothing he would have done any differently than his brother.
Now you might believe that George W. simply had a string of bad luck. Possibly. It is also possible that the man who rightfully characterized himself as "the decider" made the worst series of decisions of any president in history.
His office was seeing a lot of communication in the summer of 2001 that Condi Rice - his National Security Adviser - categorized as "Osama bin Laden determined to strike in US." He decided to vacation at his ranch for the whole of August before 9-11.
15 of the 19 9-11 hijackers were from Saudi Arabia. Not one was from Afghanistan or Iraq. Bush decided to invade Afghanistan and Iraq.
Lawrence Lindsey was director of the National Economic Council when the invasion of Iraq began. Donald Rumsfeld estimated the Iraq war and occupation would cost $50 billion. Lindsey suggested it might cost $200 billion. Bush decided that Lindsey should be "forced to resign" and Rumsfeld should be trusted. So far, the attack and occupation of Iraq has cost about $2 trillion, 10X Lindsey's offensive estimate.
Never in the history of this amazing country has any president decided to finance a war with a tax cut. Well, not until George W. made that decision. Dubya inherited a budget surplus of $236 billion . The year he decided to invade Iraq with a tax cut, he created a deficit of $378 billion, a swing of $614 billion from just three years earlier. By his last year in office, his annual deficit had grown another trillion dollars. From Clinton's last year to Bush's last year, the deficit grew by as much as Canada's entire GDP. Only 10 of the world's 200-some countries have GDP larger than Canada.
Well it may have been expensive, but at least Iraq was worth it, right? It's hard to imagine how you'd argue that.
2,977 people were killed on 9-11. In the invasion and occupations of Afghanistan and Iraq, 6,717 service people have died and even that tragic number is only 4% of the 150,000 Iraqis who've been killed since our invasion.
We pumped enormous amounts of money, armaments, and military expertise into that area. ISIS is now well armed and has been able to tap into outrage to make that region a parody of Bush's vision of Iraq as a "beacon of hope." I'm not sure what data would support the claim that Iraq was a success.
Putting aside the fact that randomly pulling a professor from any American university's department of policy would yield someone more grounded in facts and sound theory than Jeb, it is enough to be alarmed that this man sees no reason to apologize for American (read, my brother's) foreign policy. All of these atrocious outcomes and THERE IS NOTHING TO LEARN HERE is the conclusion the man is hoping we will make. Given he can't admit that his big brother made a single mistake, he can't learn a thing from Dubya's disastrous administration. With no learning, there is no progress.
The Republican Party has been given an IQ test. If they choose Jeb, they will prove that they've slipped from linkage to facts and theory into the realm of ideology. Ideologues don't deal in theories. They deal in unchanging principles. They don't learn and adapt. They persevere. They don't just reject evolution in theory. They reject it in practice.
The Republican Party emerged in the mid-1800s when the Whig Party died. If Republicans decide they are ideologues rather than pragmatists, if they nominate another Bush or someone like him, they will follow the path of the Whigs, dying out as the last of the baby boomers who so fondly remember Reagan die out. Curiously, this party that is home to so many who resist science has a simple choice: evolve or die. That evolution starts with - if not an apology for past policies than at least a radical change in them. It is harder to imagine Jeb Bush leading this change than it is to imagine Tito Jackson becoming more famous than his siblings Michael and Janet.
24 February 2015
20 February 2015
Confusing STEM Education, Innovation and Entrepreneurship
Innovation is a form of technological invention. Human genome sequencing that results from a swab from the inside of your cheek, for instance. Or mounting lightweight cameras onto helmets or drones to capture video of skiing from the perspective of the skier or the surfer from the perspective of a sea gull, for example.
Entrepreneurship is a form of social invention. 23andMe, the company that sells a personal genome test, for instance. Or GoPro, the company that sells cameras for use in odd places like drones or dashboards, or example.
The skills for innovation and entrepreneurship can overlap but they don't have to. By 1900, Andrew Carnegie was probably the richest man in the world. Carnegie's early success depended on a process patented by Henry Bessemer. Carnegie was a businessperson who knew how to solve new problems with strong, affordable steel that could be used to build skyscrapers and railroads. Steve Jobs did not invent the computer (although his partner Steve Wozniak did make some advances in circuit board design that helped to evolve it).
You could be innovative but not entrepreneurial. R&D labs are full of brilliant scientists who really could not tell you the commercial application of their efforts. And of course you can be entrepreneurial without being innovative. Starbucks original founders did not invent coffee roasting. McDonalds' Dick and Mac (fortunately for us, their most famous burger was named after Mac) did not invent the hamburger. The original founders of these companies were not even the ones who made the brands wildly successful. Ray Kroc and Howard Schulz have their names forever associated with McDonalds and Starbucks because they made them an international success and took the companies public.
There is a great deal of emphasis on STEM education - science, technology, engineering, and math majors. This is nice. It helps with innovation and we can always use more STEM graduates. They're probably the group least likely to be unemployed.
But even STEM graduates might not become innovators. They might not develop new technologies and products. That depends on particular sorts of institutions as varied as good grad schools, a strong financial community willing to bet on long-shots (venture capitalists, for instance) and strong R&D labs within universities and corporations.
And of course, those innovators may never become entrepreneurs. The skills required for product invention do not automatically lend themselves to entrepreneurship.
On that note, here is a fascinating chart that shows the gap between STEM and innovation. The gap between innovation and entrepreneurship is even wider. The policies that encourage each are very different but it's not obvious that policy makers make that distinction.
30 January 2015
Why Corporations Could Get Higher Returns Than VCs
Daniel Kahneman is the only psychology professor to have
won a Nobel Prize in Economics. His studies with Adam Tversky on how people value things is one
of the reasons. They suggest something counter-intuitive about risk.
In one study, Kahneman ran a few scenarios with coffee
mugs from a person’s alma mater. In one scenario, he gave people the mug and
let them “take ownership” before offering to buy it back from them. In the
other study, he let people buy the mug that was not yet in their
possession. On the surface, you would think that they would value the mug the
same way in both instances, but they didn’t. He had to pay, on average, $7 and
some change to buy the mugs back from people. By contrast, he had to sell the
mug for about $3 and change to get them to buy when they did not already own
it. Kahneman’s conclusion was that people put a higher price on loss than they
do gain. It is more painful to lose what you have than never get something
comparable. He had to pay people twice as much to give up their mugs as they
were willing to pay to buy them.
This makes sense. You might feel the pang of a
relationship that fails to materialize but that is nowhere near as devastating
as a divorce. Not getting the job is rarely as painful as being laid off. Loss
is painful and we put a premium on avoiding the loss of valuable things.
This is one reason that Warren Buffet is worth so much. He
sells insurance. People pay a premium to avoid loss. Richard Thaler discovered
that people would not pay more than $200 to avoid the 1 in 1,000 chance of immediate
death, which suggests they value this added probability about the same as a smart
phone. But if you offer to pay someone to accept 1 in 1,000 odds of immediate death,
they refuse it even for $50,000.[1]
Just to be clear on this oddly paradoxical approach to
risk, here are the scenarios.
Scenario 1: You
have a choice between two pills to cure what ails you. The $1 pill has a one in
a 1,000 chance of killing you immediately. The premium pill eliminates this
chance. How much extra will you pay for the premium pill?
Research suggests that the average person will not pay
more than $200 for the premium pill.
Scenario 2: You
are offered pay to be in a research study, testing the $1 pill that carries a
one in a 1,000 chance of killing you immediately. How much will you demand to take
this risk?
Research suggests that the average person will not do it
even for $50,000.
Oddly, this does not result from a difference in the probability
of death: in both cases, it is one in 1,000. These two scenarios offer the exact
same risk, the exact same chance of death. One measures how little you are
willing to lose to avoid the risk and the other measures how much you have to
gain to accept the risk. The pain of loss is much greater than the allure of
gain. We do not feel so bad about losing out on big gains but we desperately
try to avoid even small losses.
These differences in how we value risk help to explain why
the derivatives, junk bond and futures markets are worth trillions. Smart
investors will buy risk from people at a discount. Now that would just be
interesting if it were not for something really fascinating that it suggest about
how corporations could use behavioral psychology and the popularization of
entrepreneurship to earn returns that venture capitalists would envy.
The prime candidates for entrepreneurial ventures are
actually people in their 30s and 40s. Their startups are less likely to fail
and reasonably so. They have more experience than people in their 20s and more
drive than people in their 50s. They have learned about processes, products and
people and typically know at least one industry reasonably well. But they have one major disadvantage in comparison to the
twenty-something crowd: they have so much to lose.
Imagine a 40 year old who has been in the industry – any
industry – long enough to have a potentially lucrative idea. He knows a cheaper
way to make an old product or has an idea for an innovative new product or how to create a new market. He also knows that executing this idea will require
capital. And leaving his job. And working at risk for at least a year – more
often 3 to 7 years. It is not hard to imagine that at 40, he has been
married for 10 or 12 years. His children are 9 and 7 and he has a small amount
saved for their college. He is 8 years into his 30-year mortgage. He is 10
years into his job and now gets 4 weeks of vacation and is fully vested in the
401(k), which is just starting to seem sizable – but still not enough for
retirement. The man has a lot to lose. Most importantly, he puts more weight on
the cost of losing all that than he does on the potential gain from his
entrepreneurial venture.
The twenty-five year old, by contrast, has almost nothing
to lose. For this reason alone, she might be the better candidate for
entrepreneurship.
If Kahneman’s studies are right, our 40 year old values
what he has now vs. what he could have at a rate of about 2 to 1. If Thaler is
right, he values it at a rate of at least 250 to 1. In any case, the emotional
cost of losing what he already has is great. He would be sick to wake up at 47
with no 401(k), no business, no money for college for his 16 and 14 year old children,
and no equity in his home. The prospect of this is more terrifying than the
hope of waking up at 47 to a net worth of $5 or 10 million and the expectation of
doubling that every 2 to 5 years. His preference for the second scenario is not
as great as his desire to avoid the first. Loss is more sharply felt than gain.
This suggests that corporations have a great deal to make
by offering entrepreneurial opportunities to their employees. Countless
employees who could be great entrepreneurs shy away from the prospect because
they have something to lose. What a corporation would have to offer as a
percentage of returns would be less – perhaps considerably less – than what a
venture capitalist or traditional banker would have to offer. A successful
venture could return considerably more to the corporation than it might to the
venture capitalists simply because the employee as entrepreneur would have so
much less to lose than the employee who leaves his job to become an entrepreneur.
[1] Peter
L. Bernstein, Capital Ideas Evolving
[John L. Wiley & Sons, Hoboken, New Jersey, 2007] p. 15.
Stay tuned. This is an excerpt from an update to The Fourth Economy: Inventing Western Civilization, soon to be released with revisions. In the 20th century, we popularized knowledge work. In this generation we will popularize entrepreneurship. This is going to be big.
20 January 2015
Why Financial Bubbles Are Becoming More Common (and Dangerous)
“Between June 1998 and June 2008 the notional[1]
value of outstanding over-the-counter derivatives exploded from $72 trillion to
$673 trillion … just under eleven times global gross product.”[2]
“The gross debt of the US financial system grew from 20
percent of GDP in 1979 to 120 percent in 2008. In the UK, the gross debt of the
financial system reached two and a half times GDP in 2007.”[3]
How is it possible to have so much capital?
One theory offered by people like former Fed Chairman Ben
Bernanke and Europe’s most respected financial commentator, Martin Wolf, is
that we have a savings glut. There is no way to distinguish between a savings
glut and an investment dearth but in either case, the supply of capital is
great enough that interest rates hit zero. (When something is scarce, its price
goes up. When there is a glut of it, the price goes down. Interest rates are
the price of capital and interest rates have been at or near zero for most of this new century.)
A glut of capital would have seemed like a fantasy to
people living in the second economy (1700 to 1900) when capital was the limit in the same way
that an all-you-can-eat buffet would have seemed like a dream come true to
medieval peasants. But excess can bring its own problems and the financial
crisis of 2008 that triggered the Great Recession was a reminder that a
financial system can be weakened by either too little or too much capital.
Capital was the limit to progress in the second economy. Capital
made the biggest difference and was the source of the most new jobs and wealth.
In most – but not every – instance, more or better capital was the answer to
the question of how to make progress. If we imagine the economy as requiring four factors of production, the second economy looked like this.
During the second economy, to make more capital was to
make more progress. Limits define the output of a system. The two-lane stretch of highway determines how many cars pass through in rush hour, not the three-lane stretch beyond it. In 1700, there were hardly any machines able to do work. Instead, work was manual. More machines, more factories, and more stocks and bonds to finance them all increased total economic output.
But with an investment dearth, capital is no longer the
limit. In the fourth economy, the new limit is entrepreneurship. Our economy
looks more like this now.
To create more credit, to generate more capital, is like
building up a glut of products between your second and fourth machine in the factory.
It is the equivalent of increasing the capacity of the capital without a
corresponding increase in knowledge workers or entrepreneurs. In the bubble
leading up to the financial crisis of 2008, financial markets were wildly
productive. That would have been a good thing had entrepreneurs been hiring
workers at record levels, but they were not. The result was a huge bump in capital
that simply bid up the price of existing assets (like homes and stocks) rather
than creates them.
This is akin to an increase in the rate at which we build
up inventory (the product that passes through machine two) without increasing
the rate of products that leave the factory (product that passes all the way
through machine four). Inventory can only stack up for so long before the
second machine has to halt production. This becomes the cycle of booms and
busts when the second machine is capital. More capital at the dawn of the
fourth economy created bubbles. Once we popularize entrepreneurship, this rise
in capital output will be hugely beneficial.
For now, though, we have trillions in capital sloshing
about the globe in search of returns that, like waves in a bathtub, can only go
so far in one direction before it will reverse direction. In the late 1990s, it
flowed into the stock market and drove up prices there, first creating a bubble
and then a bust in 2000 when it left. In the mid-2000s, it flowed in the
housing market, driving up prices there, first creating a bubble and then a
bust in 2008 when it left. Capital has become dangerous, driving up the price of assets every time it sees one as key to returns and then driving down their
price once it realizes the gains are the result of a surplus of capital
bidding up the price of a scarcity of assets.
That dynamic was at work in the 2008 financial
meltdown. When markets fell, assets as varied as real estate and stocks dropped tens of trillions
of dollars. About 30 million people
around the world
lost their jobs and millions lost their homes.
Until we get better at developing entrepreneurs and making
employees more entrepreneurial, we will have an investment dearth. We continue to get better at making capital but that is no longer the limit. Once we get
better at making employees more entrepreneurial, we will have a good use for
such huge amounts of capital. At that point, we might even shift from an
investment dearth to an investment glut (or savings shortage). At that point,
there will be an abundance of opportunities for capital. Until then, an excess
of capital will continue to create a series of bubbles and busts.
[1]
Notional value inevitably exceeds the market value of a derivative. You might
have a derivative based on a $100 stock price but would reasonably expect its
value to move only 5 to 20% of that, a fraction that would set the market value.
“Still, the market value of derivatives rose from $2.6 trillion to $35.3
trillion in December 2008, itself more than half global output,” Wolf writes.
[2]
Martin Wolf, The Shifts and the Shocks:
What We’ve Learned – and Have Still Yet to Learn – From the Financial Crisis,
[Penguin Press, Kindle Version, 2014] p. 128.
[3]
Wolf, The Shifts and the Shocks, p.
129.
09 January 2015
This Decade's Extraordinarily Good Job Creation Performance
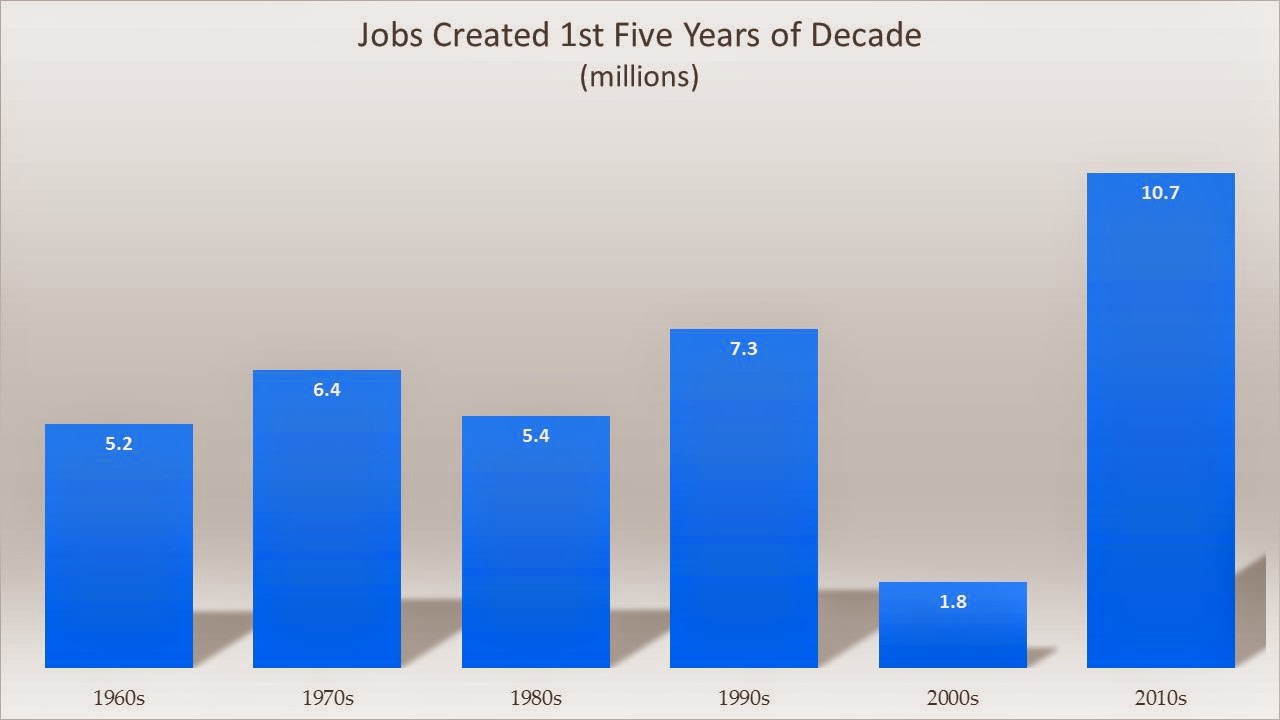
December's job report completes the fifth year of this decade. So far, this has been an extraordinarily good decade.
First, a simple fact. The economy has now created more jobs in the first half of this decade than it did in all of the 1950s.
First, measured by jobs created, 2014 is the best year yet for the decade. This recovery is not slowing. Not yet.
The unemployment rate, too, dropped last year at an impressive rate, the second year in a row in which it dropped by more than 1 point. At 5.6%, it is back to what it was in the summer before Lehman Brothers' bankruptcy in 2008. Remember that in December of 2009, it was 9.9%.
So how does this compare to past decades? It stands out.
Not only has the American economy created more jobs in the first half of this decade than it did in all of the 1950s, it has easily outperformed the first five years of every decade since. 10.7 million jobs is nearly double what the economy created in the first half of the 1980s.
I wonder if the pundits will change their tune about this terrible economy before the decade is over or if they're just going to leave that to historians.
22 December 2014
Why You Should Be Blown Away by Median Wage Growth of 2.1%
Wages rose 2.1% year over year through June 2014. That's been met with a yawn but it is a phenomenal number.
2.1% doubles wages every 33 years. Sustained, a wage growth of 2.1% increases wages by 8X in a century, enough to raise the median wage of $32,154 in 2000 to $256,927 by 2100.
Does that sound outlandish? It's not. Wages grew about 8X in the 20th century. But more impressive than the increase in wages was the change in what you were able to buy over the course of the last century. At any price. I'm not sure how you would factor that into a calculation of wage growth. And the addition of outrageously cool things to buy is likely to continue. This new century has already given you new products like personal genetic analysis and a ticket for space travel.
Here is a partial list of things that you could buy in 2000 that you could not buy in 1900. A surprising number of them are quite affordable. Any one of these would be deserving of a post that explores just what it means. (One day of travel would get you to the other side of the globe? For the average person in 1900 - very, very few had cars - a day's travel meant going into town and back.) Imagine what extraordinary things a person in 2100 with an income of a quarter of a million will be able to buy for Christmas presents.
Radio
A photocopy
Ticket to a movie
A video
TV
Airplane ticket. To anywhere
Airplane
Helicopter
Rocket
Anything plastic
Air conditioner
Teabag
Microwave oven
Electric refrigerator
Safety razor
Crossword puzzle
Bra
Vibrator
Rocket
Penicillin
Antibiotics
Antibiotics
Hepatitis-B vaccine
Polio vaccine
Insulin
The Pill
LSD
Bubble gum
Nylons
Laser
Velcro
Credit card
Mutual fund share
A pacemaker
Valium
Viagra
Prozac
Computer
Personal computer
Smartphone
Video game
Email account
Website
Video conference. With anyone. From anywhere
GPS
18 December 2014
Anniversary of Verdun - Not Just Worse Than Anything We've Experienced But Worse Than We Can Imagine
Try to wrap your mind around the scale of this tragedy. 9/11 happens. 2,996 lives tragically ended on a Tuesday. The country shocked. And then on Wednesday, 2,996 more lives are taken in a similar attack. Twice in a row now, the country is incredulous. And then on Thursday, another 2,996 lives are taken. Friday, 2,996 more. Every day this happens for 100 days, from 9/11 to 12/21.
Think of how many families would be shattered, the inconceivable number of young lives cut short. The baffled and heartbroken parents and siblings. Imagine how shell shocked people would become. Think about how hard it would be for the nation to absorb a loss of that magnitude, to even make sense of it. Imagine how much it would change us.
The Battle of Verdun ended on this day 98 years ago. In this single battle, 300,000 were killed.
By the time that World War 1 was over, 16 million people had been killed, 7 million of them civilians. 16 million is the equivalent of a 9/11 every day for nearly 15 years. This in a world where total population was about one-fourth of today's population.
It's not just that we really have no equivalent experience in our lifetime. We can scarcely imagine it.
Thank you Thomas for the reminder.
13 December 2014
Halfway Point of the Decade that Will Transform the Middle East
Arab Spring seems
to have begun with Mohammed Bouazizi, a 26-year-old Tunisian with 6 kids.
Police had confiscated his vegetable cart – his livelihood - in December of
2010. When officials refused to hear his complaint, he protested by setting
himself on fire. Within a month protesters had ousted Tunisia’s government.[1]
This was the start of Arab Spring, a contagion of protest and revolution that
swept through the Middle East. By 2013, the heads of state in Tunisia, Egypt, Libya,
and Yemen had been chased from office and civil wars had started in two
countries and protests in half a dozen others. These were protests orchestrated
through Twitter and Facebook and played out in the streets with guns and tear gas. Secularists and religious groups have agreed to oust dictators but now
have to agree about how to govern.
For me, this picture of the Camel with Google camera mounted on it seems to capture the Middle East's current, odd juxtaposition of old world and new better than anything I could imagine.
Evolution is hugely defined by environment. The Middle East is going through democratic revolution and reform in such a very different environment than did the West that it will be fascinating to see what it produces. Hopefully, among the things it produces there will be at least a few more pictures like this.
10 December 2014
Post- 9/11 Interrogations
This week's release of information about the CIA's torture glosses over something fundamental about the interrogations.
Kurt Eichenwald, in 500 Days: Decisions and Deceptions in the Shadow of 9/11 recounts how American interrogators worked at Guantanamo Bay. Reading it, I was struck by how odd their assumption was about the folks they'd captured. The prisoners at Guantanamo were - most of them - soldiers of some kind. Many were from Afghanistan, a place where 92% of the people don't even know about 9/11. (This is not a place where the average person watches the evening news or surfs the Internet for investigative reporting. And where - between Russians and the Taliban - they've had their own atrocities to deal with.)
Imagine that al-Qaeda soldiers captured some American soldiers, took them to an island in the Middle East, and interrogated them about Bush's secret plans for fighting Islam or details about Cheney's underground bunker. It wouldn't even matter if these al-Qaeda interrogators were polite when they asked questions of the American soldiers. It would still be stupid. It wouldn't matter if the al-Qaeda interrogators offered the Americans access to American football games and BBQ or tortured them. No kindness or threat would change the fact that these men were ignorant of what al-Qaeda wanted to know.
These prisoners at Guantanamo Bay were largely low-level soldiers who were nonetheless interrogated daily, as if they had great secrets to reveal. They didn't. The men working at Guantanamo were under pressure to produce results and they tried everything from kindness to threats to torture and nothing worked for the simple reason that the men they'd captured didn't know anything useful.
As with so much in the wake of the Bush Administration's reaction to 9/11, the folks executing policy were struggling to build a skyscraper on a foundation of reinforced cardboard. Even on a good day, when you're given an impossible task, what you try may be unreasonable. And on really bad days, what you try may be immoral.
08 December 2014
Needs No Further Explanation
Or perhaps more precisely, I couldn't provide any explanation. This just seems to capture something perfectly.
The Arguments About Keynesian Economics Are Almost Never About Keynesian Economics
Keynes had a major insight into economics that people still seem to miss. It has to do with equilibrium and it plays out something like this.
1.
Capital markets are essential to a thriving economy. Without investors willing to fund new schools and factories, new businesses and non-governmental organizations, we'd have no innovation, no growth, no creation of wealth or jobs. As an economy becomes more dynamic, this steady infusion of investment becomes more important just to sustain normal growth and employment.
2.
During a period of healthy growth, the equilibrium for capital markets and labor markets are coincident. Letting investment markets do their natural thing will result in new jobs and economic expansion.
3.
The equilibrium for capital markets can shift. One day the price of capital can induce savers to invest and the next day it can convince them to hold their money in cash rather than make loans or fund new businesses.
4.
This new equilibrium in capital markets shifts the equilibrium in labor markets. Unemployment can spike as capital sits idle.
5.
This shift in equilibrium for capital and labor markets will drive down GDP. Sales will fall.
6.
At this point, it's perfectly rational for every sector to sustain the recession. Households without jobs won't buy. Businesses without sales won't hire. Investors without sufficient number of employed households or expanding businesses to loan to will sit on their money.
7.
In other words, at this point every "localized" market - labor, goods, and capital - will be in equilibrium. The good news is that the economy is stable. The bad news is that it has reached stability at recessionary levels. This general equilibrium needs to shift before it will make sense for investors, households, and businesses to change their behavior. There is nothing happening in the two other markets to drive a change in the third.
8.
Government can make changes that will shift equilibrium in all the "localized" markets. By spending more, by cutting taxes, by putting more money into circulation or lowering interest rates, it can engineer temporary growth, helping to put an economy back on track for steady expansion. It can disrupt the equilibrium in the localized markets to get things moving again.
Valid rebuttals to Keynesian economics include criticism about a governments' ability to time stimulus, the level of downturn deserving of Keynesian stimulus, and the degree to which a Keynesian style intervention needs to be coordinated with other countries to be effective. You could even argue about whether expectations might mitigate the effect of such government policies.
Invalid rebuttals include "I don't like big government." Keynesian policy recommendations are incidental to the size of a government. Countries like Denmark (where government spending is 58% of GDP), Sweden (51%), Germany (45%) the US (41%), Mexico (27%), Singapore (17%), or the Philippines (16%) can all engage in Keynesian policies. Whether you want to emulate Southeast Asia or Northern Europe is irrelevant. Whether your long-term target for government spending is 50% of GDP or 15% of GDP, government spending can still be increased in the short-term in response to recessions and downturns. You can induce capital markets to engage in ways that stimulate the whole economy.
For me, the real genius of Keynes was his realization that reaching equilibrium in capital markets didn't automatically ensure equilibrium in the general economy. Before Keynes, we only had economics. After Keynes, we had microeconomics and macroeconomics. His policies were key to creating conditions that allowed the limit to shift from capital to knowledge workers.
07 December 2014
The One Piece of Art that Most Defines the Renaissance
Much of Renaissance art is priceless. If you could own a work by Michelangelo or Botticelli or Raphael you would not only have sublime art to gaze on but could - any time you wanted - sell it for more money than you could hope to spend in a lifetime. And rightfully so. It's not just amazing art. As cliche as it sounds, Renaissance art changed how we looked at the world.And on that note, I think Peter Bruegel's Landscape With The Fall of Icarus from 1555 best depicts the change from focusing on the supernatural to the natural. It shows how the Renaissance changed how we in the west looked at - and saw - the world.
The most obvious thing here is the farmer plowing the land. He's at work. Just behind him is a ship likely laden with goods from or to another land. A shepherd over the shoulder of the farmer is contemplating the sky, perhaps daydreaming or perhaps looking for signs that would help him to forecast the weather. Oh, and in the water before the ship is Icarus who flew too close to the sun.
Icarus's story is amazing. He flew to freedom with wings his father had constructed of feathers and wax. His father warned him not to fly too close to the sun lest the wax melt and the wings be unable to keep him aloft. Of course Icarus was unable to resist the exhilaration of flying high and, indeed, his wings failed him, causing him to fall out of the sky into the sea to his death. Not only are a host of themes bound up in this story of Icarus (among other things he's a lesson in hubris) but the idea of freedom through flight is sort of amazing. Especially to ancient Greeks and even 16th century Dutch.
But what Bruegel does with this incredible story is relegate it to a corner of the painting. Myth has given way to business. The farmer could not be less impressed with Icarus's foolishness.
We can hardly imagine how completely the promise of heaven or threat of hell defined medieval life. For most Europeans from the fall of Rome until the discovery of the new worlds (about a 1,000 years, from roughly 476 to 1492) business concerns like plowing a field were a distant second to religious concerns. By the time of this painting, in more developed places like the Netherlands and Northern Italy, this had begun to shift. And Bruegel's painting rather brilliantly captures this. A great deal of how we look at the world is defined by where we look. By Bruegel's time in the mid-16th century (Columbus had "discovered" the "new" world and Magellan's crew were the first to circle the whole world), people realized that the natural world was full of the unknown, full of promise, full of riches. It deserved our full attention. At least during harvest or planting.
06 December 2014
In Which Your Blog Author Manages to Turn a Big Stock Market Prediction into a Very Small Gain
On October 13, I made a prediction about job numbers and a prediction about the stock market.
Here is the prediction I blogged about the stock market.
"The S&P 500 is up only 1.4% from the start of the year. ...
I'd look for a sharp rise in the market before year end. I think between now and December 31, the market could easily rise 5% or more. The result will be a fairly unimpressive year but it will have gotten there in spectacularly volatile fashion."
I predicted a rise of 5% or more and the S&P is up 10.7%. I'd like to file that under accurate prediction but of course the market could still fall spectacularly before 2015, so let's mark that as tentative.
Here is the prediction I tweeted about job numbers.
"Prediction:
Job report for October (released 7 Nov) will be for over 300,000 new jobs."
I jumped the gun on this one. Even with Friday's upward adjustment to the numbers, it looks like the economy created only 243,000 jobs for October. It didn't break 300,000 until November. So, that's a miss on timing.
Finally, in spite of getting the market prediction right, my own portfolio limped along in that time. The S&P is up 10% since I made my stock market prediction and my portfolio is up just 2%. Pretty pathetic. So that's a big miss.
My final score on predictions:
1 right (so far)
1 right about magnitude, wrong about timing
1 major miss in applying big insights into personal victories (the sort of thing that might have happened to me once or twice before).
So, 1 for 3. That sounds better in baseball.
05 December 2014
Is This Record Streak of Job Creation Finally Raising Wages?
Today's job reports makes for some great facts.
In November, the American economy created 321,000 new jobs. 365,000 jobs were announced today, though, because the job creation numbers for September and October were revised upwards.
Since 2000, there have been only 2 months with job gains of more than 365,000.
It has been nearly 20 years since we've had 10 consecutive months in which the economy has created at least 200,000 jobs.
This month's positive number means the current uninterrupted streak of positive job numbers is now 50 months, breaking last month's record for longest streak since the US began keeping records in 1939.
Even if the economy creates zero jobs this month, 2014 will be the best year for job creation since 1999. That is, this is already the best year of the new century.
While the unemployment rate held steady at 5.8%, it is down 1.2% from last year and this sustained rate of job creation might finally be putting upwards pressure on wages.
There is also really promising news about wages. In the October report, wages were up only 0.1% from the previous month. This month, they were up 0.7%. Now 0.7% is almost surely unsustainable. (That would translate into a 8.2% raise in wages for the next year, a delightful prospect that's more fantasy than possibility in light of the last couple of decades but a rate that we actually hit in the 1970s and 1980s.) But such a sharp upwards trend in the context of lower unemployment rate and strong job growth suggests that we might finally be moving beyond the prolonged period of wage stagnation that has characterized this new century. If so, that could be the best news yet.
03 December 2014
File Under "Reasons to Be Optimistic." Is Entrepreneurship the Reason US Recovery is Stronger Than Europe's?
The Global Entrepreneurship Monitor (GEM) report on entrepreneurial activity is promising on two counts for the US. First, it shows that the steady trend for entrepreneurial activity here is upwards. Second, it shows a sharp drop in "necessity driven entrepreneurship," suggesting that the job market's recovery won't inhibit this rise.
The above chart shows the percentage of the population between 18 and 64 who are either a nascent entrepreneur or owner-manager of a business. While this number dropped through the worst of the recession, it has now recovered to its best levels in the century. (At 12.7% it is essentially where it was in 2012, when it hit 12.8%.) That's great news.
When financial markets convulsed and credit disappeared, it made sense that the number of new business ventures would drop. But of course as layoffs spiked, it also makes sense that more people would be forced into entrepreneurship. If you can't find a job, you have more incentive to make one.
Well, the GEM tracks the relative prevalence of this ""necessity driven entrepreneurship," as well. It captures the percentage of folks who have gone the entrepreneurial route because they had no other options for income.
As you can see, Spain - where unemployment is still above 20% - continues to rise in necessity-driven entrepreneurship. Such entrepreneurship is too often driven more by fear than hope. In the US, though, there has been a sharp drop in this type of entrepreneurship from 37% to 21% of total entrepreneurial activity. As the labor market has recovered, fewer Americans are forced into entrepreneurship.
Finally, Kauffman tracks entrepreneurs who are currently setting up businesses. These are ventures that still haven't paid salaries but promise to create jobs and wealth. This is a measure of early-stage startups. Here, the US stands out with rates that have doubled in the last few years and are double those in most of Europe.
This nascent entrepreneurship rate is a pretty shocking number, really. Not only has it jumped from 4.9% in 2010 to 9.2% of the workforce in 2013, it is more than double the rate in the UK (3.6%) or Norway (2.9%).
Most of these startups will fail. Still, you miss all of the new jobs that you don't try to create. This bodes well for the US and could be the simplest explanation of why Europe's GDP is close to dipping into yet another recession even as the US is flirting with GDP growth of 4% and about to extend its record for consecutive months of job creation. It seems to me as good a reason as any for optimism.
28 November 2014
There's a Bigger Issue Here - The Norms We Accept For Police Shootings
27 November 2014
A Life in Motion Tends to Stay Imbalanced ...
A young friend who became a dad this year was commenting about how he has to cut out personal activities now. I was probably in my thirties or forties before I realized that when people said, "Hard work and sacrifice" they weren't making the two synonymous. Sacrifice means giving up something you value.
You don't pull off any really important "project" like starting a business or raising a child without making sacrifices. In the end, a balanced life is made up of some extreme moments, prolonged periods of imbalance. At least if you want to accomplish anything much. Walking is a controlled fall, action that harnesses imbalance.
25 November 2014
Why Our Media Will Make it Difficult for Anything Good to Come of Ferguson
Protests flared up around the country and violence and looting resulted in at least one death last night in Ferguson following the Grand Jury's decision not to indict Darren Wilson. So what's the good news? All of this media attention and turmoil is in the wake of the killing of an 18 year old boy rather than a man of Martin Luther King's stature. That, for me, signals hope. But it's a signal that could get lost in our media's noise.
I've become increasingly disillusioned with our for-profit media. A for-profit media is motivated to increase revenue. If that means making a big deal about Kim Kardashian's butt than they'll do that. Real progress is slow and takes some sophistication to cover. It's like writing a novel: you have to be skilled to get it right and it takes a long time. The conversation the media needs to facilitate now is one about causes and cures for the huge cost of being a black American.
The simple fact is that a black man can expect to die in his 60s and a white man in his mid-70s. (White males life expectancy is 75 years and black male's is 6 year less.) Household income for blacks is only 59% of whites' and wealth of black households is 20% of white households.
There are only two explanations for this. The first is that blacks are inferior and this is a natural consequence. We can dismiss the fact that blacks - once excluded from sports and pop culture entertainment because of their supposed inferiority - have proven that they're more than able to compete in their athleticism, comedy, creativity and music ability. It's possible that they really are as good as whites on a variety of performance measures but just happen to be bad at business. Or it could be that business relationships are one area where it's still common to be unscientific and instead rely on our judgments that are colored by folklore, gut, instinct, and racism that we scarcely admit even to ourselves. Which brings us to the second explanation for the gap between whites and blacks: racism.
It's obvious that there is still plenty of racism alive today. It's less obvious that when we're talking about issues like wealth and income, racism suffered by your grandparents puts you at a disadvantage. Privilege and opportunity - for good or for bad - dominoes across generations. Even if we eradicated all racism today, blacks would still take generations to catch up simply because privilege and opportunity provide advantages that take generations to dissipate. Even if the average American's income stopped growing for decades, it would still be higher than that of China's.
Good policy starts with facts and then makes plans to change them. It doesn't ignore facts. It doesn't defend the status quo. And it looks beyond the stories of heroes and villains to systems. It's true that privileged whites screw up their advantage sometime. It's true that disadvantaged blacks rise above obstacles. But it's not the folks who do well or poorly in spite of prevailing norms that should concern policy makers. The focus of good policy is on improving the distribution of the whole population, not putting a spotlight on outliers. And of course, outliers - the violent youth or wealthy businessman - are the focus of our media, which makes it so hard to hope for policy that will change normal rather than spotlight the extremes.
20 November 2014
Obama's Big Miss on Immigration Today
Obama missed a huge opportunity today. We may have 10 million illegal immigrants. Let's assume that half of them have jobs. Just think of what an incredible jobs program he could have launched.
One, he could have announced the forced deportation of all illegals. That would require hundreds of thousands of people searching records and houses to find them. It would require hundreds of thousands of swat team members to raid homes and work places to seize and deport these people, thousands more to drive them south. (All of them should be driven south. Even the Canadians and Germans who are here illegally. Let them sort out their troubles with AeroMexico.) That alone could create jobs for a million Americans over the course of 12 to 36 months.
Two, once the 10 million illegal aliens were deported, we'd have 5 million jobs to fill. (Well, maybe not a full 5 million. We would have - of course - lost 10 million consumers, so demand might dip a bit.) Those young men and women in swat gear who rounded up the illegal aliens could then take those jobs, picking fruit, changing sheets, and cooking meals.
If only Obama were more visionary, more committed to creating jobs.
Biden: Why is America Able to Reinvent Itself? An Inherent Skepticism for Orthodoxy
I love Joe Biden. Today Biden addressed a group of entrepreneurs in Morocco. He spoke about the importance of entrepreneurship and the path towards it.
So what is required to prosper in the 21st century? What does it take?
It takes an education system, but one that is universal, open to all, including girls and women, that trains people to be skeptical. I was meeting with a man many of you know, a wise man from Singapore named Lee Kuan Yew. He was asking me why did I think America was able to reinvent itself so often. I said, because stamped into the DNA of every naturalized American, as well as native born, is an inherent skepticism for orthodoxy. You cannot fundamentally change the world without breaking the old. It takes a value system that gives people the freedom to try and to fail, or as they say in the fabled Silicon Valley, fail forward, without being criticized.
Subscribe to:
Posts (Atom)